The landscape of "미니 암 보험" or mini cancer insurance is crucial for those seeking affordable and focused coverage against cancer. This guide delves into the specifics of these insurance plans, highlighting their benefits, limitations, and the growing significance they play in healthcare financing on a global scale, emphasizing the need for strategic selection to align with individual health needs and financial capabilities.
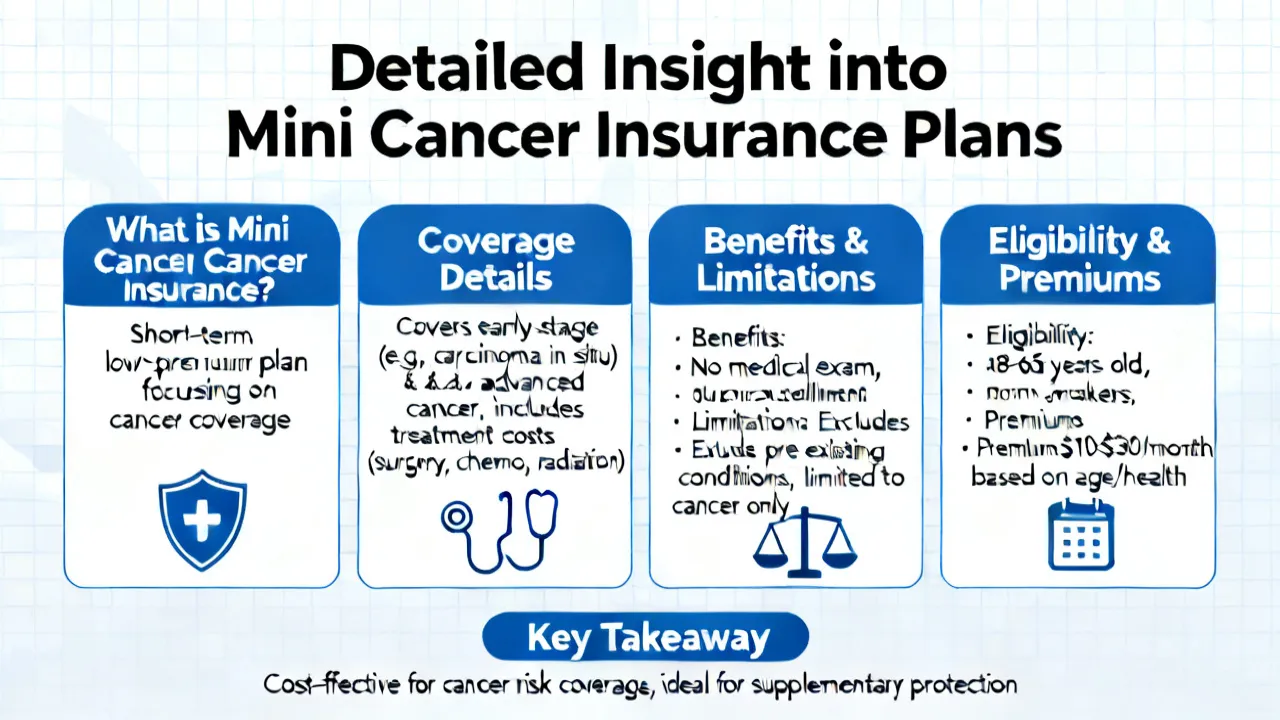
The growing prevalence of cancer globally has underscored the necessity for comprehensive and accessible insurance options. Among these, "미니 암 보험," or mini cancer insurance plans, have emerged as a crucial product in the insurance market, providing an essential safety net for individuals seeking specific coverage for cancer-related treatments without the burden of a full-scale policy. These plans cater to a demographic that is increasingly concerned about the financial implications of a cancer diagnosis, especially as treatment costs continue to rise. The idea behind mini cancer insurance is not only to offer financial relief but also to enhance peace of mind for policyholders and their families during challenging times.
Mini cancer insurance, as implied by the term, offers targeted insurance coverage for diagnosed cancer without the extensive and sometimes overwhelming coverage that full health insurance entails. This type of plan typically offers a lump sum payment upon diagnosis of cancer, helping policyholders to manage out-of-pocket expenses related to treatment, medication, and other associated costs. The fundamental premise of mini cancer insurance is to ensure that individuals have immediate financial support upon a cancer diagnosis, allowing them to focus on healing rather than financial burdens. Unlike traditional health insurance, which may cover a broad range of conditions, mini cancer insurance zeroes in on one of the most feared health issues, making it a crucial financial tool in an increasingly health-conscious society.
Several compelling reasons may drive individuals to consider mini cancer insurance:
Key elements commonly found in 미니 암 보험 include:
| Aspect | Feature | Benefit |
|---|---|---|
| Coverage | Specific to cancer treatments | Ensures that resources are fully dedicated to cancer care. |
| Premiums | Lower than comprehensive plans | More accessible for individuals seeking cost-effective solutions. |
| Payout Structure | Lump sum payment | Provides immediate financial support upon diagnosis. |
| Policy Duration | Varies from short to long term | Flexible duration options to meet different financial needs and life stages. |
| Renewability | Can be renewable based on terms | Continuity of coverage can be assured with proper terms. |
The cost of mini cancer insurance premiums can be influenced by various factors, including:
The mini cancer insurance market is projected to grow consistently as awareness about its benefits spreads. This trend is driven by rising cancer incidences and a shift toward preventive financial planning. Awareness campaigns by non-profits and health organizations are contributing to an increase in the acceptance of this form of insurance, educating the public on the financial ramifications of a cancer diagnosis. Additionally, insurance providers are increasingly offering more flexible options to attract a wider audience, including tiered plans, where policyholders can select various levels of coverage, further enhancing their ability to tailor their insurance experience.
Moreover, with the advent of telemedicine and ongoing advancements in treatment options, insurance plans are evolving to include virtual consults and treatment options, which can drastically reduce costs associated with travel and time off work. The integration of technology into health care is reshaping how cancer treatment is approached and, by extension, how it is insured. These market developments are positive indicators for the growth of mini cancer insurance, ultimately benefiting consumers by providing more personalized and accessible options aligning with modern healthcare delivery models.
The lump sum payout provides immediate financial flexibility, allowing policyholders to address various needs such as treatment costs, travel for care, or managing household expenses during treatment. This one-time payment can be particularly useful as patients may face substantial unexpected expenses during their treatment journey, and dealing with financial strain can add stress at an already difficult time.
While age requirements vary by provider, many insurers offer plans to individuals from their early 20s to those in their late 60s, with premium differences reflecting age-based risk. It's common to see plans designed to ensure that different age groups are appropriately covered, considering the changing risks associated with age. Some insurers even provide plans targeted specifically at seniors, who may face unique health challenges.
Mini cancer insurance is designed to be supplementary, focusing exclusively on cancer, and does not replace comprehensive health insurance, which covers a broader range of medical services. It’s important for individuals to maintain standard health insurance to ensure that they are adequately covered for other medical conditions and emergencies. Combining mini cancer insurance with a full health insurance policy provides a more robust safety net.
Policies often cover a wide range of cancers, but it’s crucial to read the specifics of each plan. Many mini cancer insurance plans cover major cancers such as breast, lung, colon, and prostate cancer, while some may also provide coverage for less common types. However, exclusions can vary between carriers, so understanding the terms and conditions is essential.
To assess if mini cancer insurance is a suitable choice, consider your family medical history, your lifestyle, and current health insurance. If there’s a significant gene-related risk of cancer or if you have a higher risk due to lifestyle (like smoking), mini cancer insurance may be particularly beneficial. Additionally, analyze if your current coverage effectively addresses the potential costs of cancer treatment, factoring in that standard health insurance may not fully cover such eventualities.
In conclusion, 미니 암 보험 offers a targeted and financially viable option for those prioritizing cancer coverage within their overall health insurance strategy. As the healthcare landscape evolves, these plans present a significant opportunity for securing essential financial protection against one of the most critical health challenges today. Additionally, the ongoing dialogue about cancer prevalence, evolving treatment technologies, and heightened awareness of genetic risks continues to shape the necessity for tailored insurance products like mini cancer insurance. As such, individuals are encouraged to explore these options further, consulting with insurance advisors to tailor their coverage to their specific needs.
With the ongoing changes in both healthcare and insurance technologies, mini cancer insurance stands as a crucial avenue for individuals aiming to secure not just health coverage but a better quality of life during challenging times of uncertainty. Understanding these nuances can empower individuals to make informed decisions regarding their health and financial wellbeing, ultimately leading to a more stable and prepared stance in the face of potential health adversities.
Furthermore, it is also advisable to regularly review insurance options as the market evolves. With the rise of digital tools and platforms that simplify comparisons and applications for insurance policies, finding the right mini cancer insurance could be more accessible than ever before. Taking the time to consult professionals or using reliable online resources can make a significant difference in ensuring coverage aligns with personal health profiles and financial circumstances.




Digital insurance companies, known as 디지털 손해 보험사, are reshaping the insurance landscape by leveraging technology to offer efficient, user-friendly services. These companies differ from traditional insurers by emphasizing digital platforms for operations, creating a seamless customer experience. This article delves into the critical aspects of digital insurance firms, exploring how they function and their benefits to consumers.

This guide delves into the realm of 다이렉트 건강 보험, highlighting its unique structure within the health insurance sector. 다이렉트 건강 보험 is a system that allows consumers to purchase health insurance directly without intermediaries, often resulting in cost savings and tailored plans. This comprehensive analysis explores its benefits, considerations, and frequently asked questions to help consumers make informed choices.

Discover the intricate process of claiming surgery costs under pet insurance (반려동물보험 수술비 청구 방법) to safeguard the health of your cherished furry companions. Pet insurance has become an integral aspect of responsible pet ownership, allowing pet parents to ensure their pets receive optimal medical care without incurring prohibitive costs. This guide provides expert insights into navigating the pet insurance landscape successfully.

This guide delves into 카이저 보험, a renowned name in healthcare provisioning. Known for its integrated care approach and straightforward insurance plans, 카이저 보험 stands as a model of efficiency in health management. By merging medical care services with insurance coverage, it aims to streamline patient experience and ensure accessible, comprehensive healthcare solutions.

As healthcare costs soar globally, mini cancer insurance plans like 미니 암 보험 become crucial for protecting the financial well-being of individuals facing cancer. This coverage, often more affordable than comprehensive plans, provides targeted benefits designed to ease the burden of expenses associated with cancer treatment and recovery. It's essential for consumers to discern their specific needs and compare different offerings.

This article explores the domain of 다이렉트 건강 보험, also known as direct health insurance, to provide a comprehensive understanding of its dynamics and impact on individuals seeking coverage. The discussion delves into the benefits and challenges of opting for direct health insurance, while also touching upon various factors such as cost-effectiveness and accessibility that influence consumer choices in the insurance market.

