This article delves into 적정 보험료, exploring how to determine the most suitable insurance premiums that balance affordability and coverage. It highlights the importance of calculated decision-making in securing financial and risk management while considering cultural elements that influence insurance choice. The piece is an expert's guide on demystifying insurance costs.
The concept of 적정 보험료, which translates to "optimal insurance premium," is a crucial consideration for individuals seeking balanced and effective coverage. Understanding how to determine and evaluate these premiums can greatly influence one's financial well-being and risk management approach. In this article, we aim to offer a comprehensive analysis of determining appropriate insurance premiums, drawing insights from industry experts, and considering cultural implications. Additionally, we will explore various types of insurance products available in the market, delve deeper into the nuances of risk assessment, and provide real-world examples to give clarity on how to navigate this essential aspect of personal finance.
Insurance premiums are payments made by the insured to an insurance company to obtain coverage. These payments ensure financial assistance in times of need, covering various risks such as health, auto, property, and life events. The challenge lies in identifying 적정 보험료, which balances affordability with adequate coverage to meet the unique needs of policyholders. An understanding of how insurance premiums are set can empower consumers, allowing them to make informed decisions that align with their financial goals and personal circumstances.
Several factors can influence the determination of 적정 보험료, varying across individuals and regions. Here's an insightful breakdown:
Determining the 적정 보험료 involves carefully assessing your needs and the available plans. Here's how you can approach this process:
Understanding the principles of determining 적정 보험료 also involves looking at real-world scenarios. Here are a few illustrative examples that demonstrate how different individuals or families might calculate their insurance needs:
Consider a young couple with one child who are looking for health and life insurance. After assessing their insurance needs, they realize that they want health coverage for routine check-ups, emergencies, and potential hospital stays. They research various health insurance plans that provide comprehensive coverage and evaluate their family’s medical history. They opt for a policy that offers a moderate premium but provides good coverage, as both parents are employed and relatively healthy.
To further protect their child’s future, they also consider a term life insurance policy with a reputable provider. They weigh the options based on the details of the policy, including the premium amount and coverage duration, and decide on a policy that would cover their mortgage in the event of an untimely demise. In this situation, they balance premium costs against peace of mind.
An older individual nearing retirement might have different considerations. They may consider long-term care insurance as part of their strategy for managing future health services. They assess their financial status, realizing they have significant savings but also rising health care costs as they age. Through discussions with an insurance broker, they determine the 적정 보험료 based on their assets and the level of care they might need. This leads them to a policy with a higher premium but one that offers more extensive home and assisted living facilities coverage.
A small business owner evaluating commercial insurance must consider various types of risks their business may face. They assess their current situation and determine necessary coverages, such as liability, property, and potentially even business interruption insurance. They consult with multiple insurers and determine their premiums based on their business size and risk exposure. Using a combination of comparisons and professional guidance, they secure a policy that seems slightly above their desired budget but promises a level of protection crucial for their enterprise's stability.
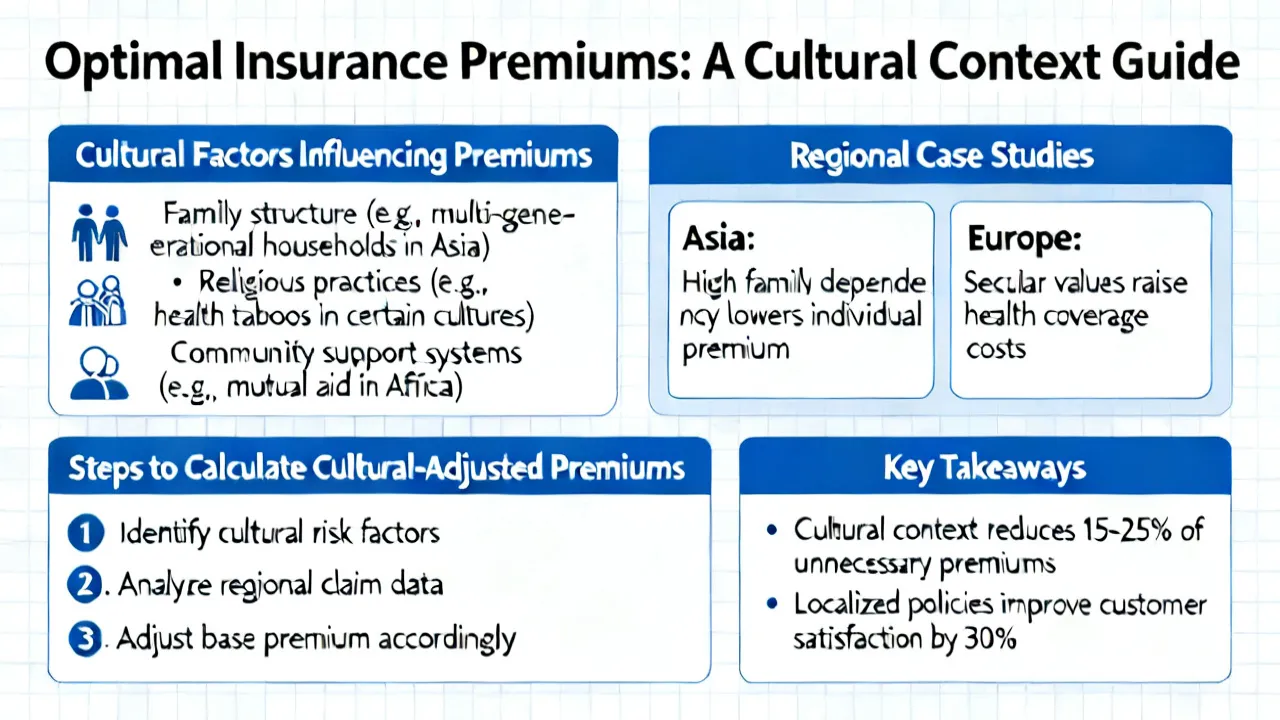
Cultural elements significantly bear upon insurance choice. In some cultures, there might be strong familial support systems that reduce reliance on extensive insurance coverage. For example, in many Asian cultures, it is common to rely on family support during emergencies, lessening the perceived need for comprehensive individual insurance. Conversely, in highly individualistic societies, there tends to be a stronger emphasis on personal responsibility, prompting individuals to seek more substantial insurance coverage. Additionally, in nations with strong social welfare systems, such as those found in Scandinavia, citizens often have less incentive to purchase private health insurance, viewing it as unnecessary due to the existing public services.
Understanding these cultural intricacies can influence how individuals determine the 적정 보험료 fitting their lifestyles and societal norms. For instance, a person raised in a collectivist culture may prioritize low-cost policies that meet minimum coverage requirements, while someone from an individualistic background might invest in comprehensive plans that offer peace of mind alongside financial protection.
The rise of technology and data analytics has profoundly transformed how insurance companies assess risk and determine premiums. Insurers are increasingly using sophisticated algorithms to analyze vast amounts of data to set more accurate premiums. For example, the use of telematics in auto insurance allows companies to monitor driving behavior, which can lead to personalized premiums based on actual risk rather than demographic averages. Consumers who drive safely can benefit from lower rates, while those who exhibit riskier driving may end up paying more. This technology-driven approach enhances fairness in premium pricing but also introduces new challenges in consumer privacy and data security.
Q1: What should I consider to find the 적정 보험료?
A1: Start by analyzing personal risks, compare different policies, assess the coverage levels you need, and consider professional consultations. Make sure to understand your risks thoroughly as they form the basis upon which premiums are calculated.
Q2: How can cultural differences impact my insurance choices?
A2: Different cultures have varying perceptions of risk and social safety nets, which can influence the importance placed on certain insurance types and coverage levels. It can also affect how individuals view the necessity of insurance in their financial planning process.
Q3: Are there discounts available for insurance premiums?
A3: Yes, insurers often provide discounts for factors such as multiple policy holdings, long-term policy agreements, safe behavior (like a good driving record), or selecting high deductibles. It is essential to inquire about available discounts when obtaining quotes.
Q4: How often should I re-evaluate my insurance premiums?
A4: It's advisable to annually review your insurance policies or whenever a significant life event occurs, such as buying a home, having a child, or changing jobs. This ensures your coverage remains aligned with changing needs and financial situations.
Q5: What tools can help in determining 적정 보험료?
A5: Numerous online tools and resources can aid in determining 적정 보험료. Comparison websites allow you to input your data and get quotes from multiple insurers, while calculators can provide estimates based on coverage needs and risk factors. Consulting agencies or brokers can also provide tailored advice based on personal circumstances.
In conclusion, determining the 적정 보험료 involves an intricate understanding of personal needs, risk assessment, and cultural influences. By systematically evaluating these elements, individuals can secure an optimal balance between affordability and coverage, ensuring effective risk management and financial security. It is recommended that policyholders not only focus on the premiums but also understand the intricacies of their chosen policies and remain proactive in reviewing them to adapt to changing life circumstances. The journey to identifying 적정 보험료 is less about a simple price tag and more about crafting a safety net that adequately supports one’s life goals and aspirations.




Digital insurance companies, known as 디지털 손해 보험사, are reshaping the insurance landscape by leveraging technology to offer efficient, user-friendly services. These companies differ from traditional insurers by emphasizing digital platforms for operations, creating a seamless customer experience. This article delves into the critical aspects of digital insurance firms, exploring how they function and their benefits to consumers.

This guide delves into the realm of 다이렉트 건강 보험, highlighting its unique structure within the health insurance sector. 다이렉트 건강 보험 is a system that allows consumers to purchase health insurance directly without intermediaries, often resulting in cost savings and tailored plans. This comprehensive analysis explores its benefits, considerations, and frequently asked questions to help consumers make informed choices.

Discover the intricate process of claiming surgery costs under pet insurance (반려동물보험 수술비 청구 방법) to safeguard the health of your cherished furry companions. Pet insurance has become an integral aspect of responsible pet ownership, allowing pet parents to ensure their pets receive optimal medical care without incurring prohibitive costs. This guide provides expert insights into navigating the pet insurance landscape successfully.

This guide delves into 카이저 보험, a renowned name in healthcare provisioning. Known for its integrated care approach and straightforward insurance plans, 카이저 보험 stands as a model of efficiency in health management. By merging medical care services with insurance coverage, it aims to streamline patient experience and ensure accessible, comprehensive healthcare solutions.

As healthcare costs soar globally, mini cancer insurance plans like 미니 암 보험 become crucial for protecting the financial well-being of individuals facing cancer. This coverage, often more affordable than comprehensive plans, provides targeted benefits designed to ease the burden of expenses associated with cancer treatment and recovery. It's essential for consumers to discern their specific needs and compare different offerings.

This article explores the domain of 다이렉트 건강 보험, also known as direct health insurance, to provide a comprehensive understanding of its dynamics and impact on individuals seeking coverage. The discussion delves into the benefits and challenges of opting for direct health insurance, while also touching upon various factors such as cost-effectiveness and accessibility that influence consumer choices in the insurance market.

