Split insurance payments, known as 분할 보험금, refer to the allocation of disbursements in insurance claims over multiple installments. This approach is often employed to provide financial relief by spreading out payments instead of a solitary lump sum. The method of 분할 보험금 can offer significant advantages and potential downsides, impacting both insurers and policyholders in diverse ways.
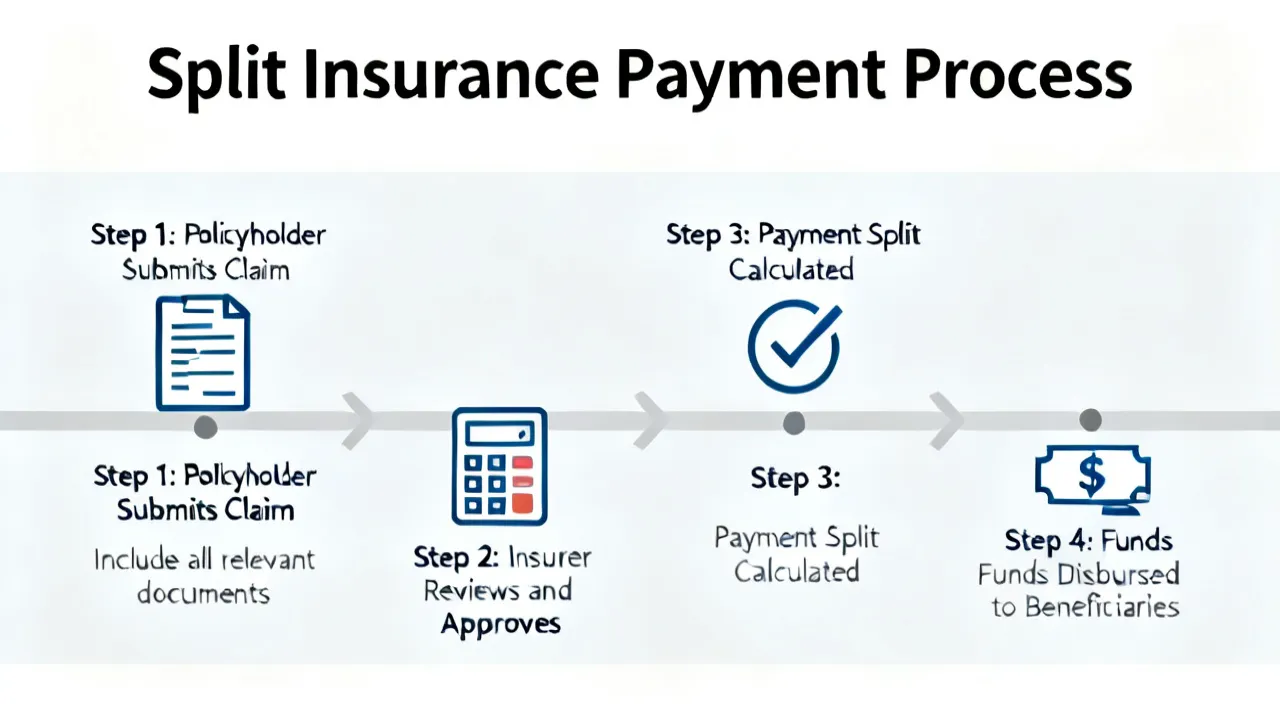
Split insurance payments, or 분할 보험금, represent a thoughtful and strategic approach within the insurance industry that allows for structuring financial disbursements over a specified period. This innovative payment method not only lessens the immediate financial burden on both the insurer and the insured, but also provides a more manageable flow of funds. But how exactly does this approach operate in real-world scenarios, and what are its array of benefits and potential pitfalls? As the landscape of insurance continues to evolve, especially in a world grappling with uncertain economic climates, understanding split payments can be pivotal for policyholders and beneficiaries alike.
In traditional insurance settlements, beneficiaries receive a lump sum once the claim is approved. However, with 분할 보험금, the payment is strategically distributed across several periods. This method of structuring payouts can be especially prevalent in life insurance and long-term care insurance policies where the magnitude of payouts can be quite significant. The installments are usually pre-determined based on the insurer's policies and a mutual agreement made with the policyholder, establishing a clear framework for all parties involved.
The division of payments can not only align with the financial needs of the policyholder but can also take into account the regulatory requirements governing the insurance provider’s jurisdiction, which may necessitate flexible solutions for different client situations. As life circumstances evolve, so too do financial needs, and this requirement for adaptability in insurance payouts highlights the importance of having a thorough understanding of these mechanics. Knowledge in this area can empower policyholders to leverage the benefits of 분할 보험금 more effectively.
This payment method offers numerous advantages that can provide both insurers and beneficiaries with a wealth of opportunities:
Despite its myriad benefits, 분할 보험금 is not without drawbacks that require careful consideration:
Ultimately, while the benefits of split insurance payments are considerable, it is vital for all parties to weigh potential drawbacks realistically. This will ensure that those involved can make informed decisions about their specific circumstances around these financial arrangements.
| Pros | Cons |
|---|---|
| Facilitates better financial management by spreading out available funds over time. | Limited access to larger amounts when urgently needed for unexpected expenses. |
| Reduces risk of premature fund depletion by providing ongoing financial support. | Potentially complex payment scheduling that requires careful planning and communication. |
| Encourages long-term strategic financial planning for beneficiaries, fostering growth and stability. | Possible increase in administrative fees related to managing the payout system. |
Understanding the different arrangements that can be made under the umbrella of split insurance payments enhances the ability of policyholders to select the most suited option for their circumstances. Below are some prevalent types:
With fixed installment plans, the beneficiary receives a set payment amount at regular intervals—monthly, quarterly, or annually. This predictability helps beneficiaries plan for their expenses, as they can count on a specific sum to come in regularly. The frequency and amount of these payments can often be adjusted based on the policyholder’s needs and the agreement made with the insurer.
In contrast, variable installment plans allow for payments that may fluctuate based on particular factors, such as investment performance or changes in the underlying policies. This type of arrangement can potentially offer larger payouts during financially favorable periods, but it does also introduce a level of uncertainty into the planning process.
Some policies might offer the option for beneficiaries to receive a lump sum followed by a series of smaller payments. This hybrid setup allows beneficiaries the ability to address larger immediate expenses while still maintaining ongoing financial support.
These payments are structured such that the disbursement amounts may depend upon the life expectancy of the beneficiary. Essentially, they are designed to ensure that financial support continues for as long as the beneficiary is alive. This can be particularly useful in cases involving minors or dependents who may require long-term financial assistance.
To better understand the implementation and impact of split insurance payments, examining real-life examples can paint a clearer picture. Here are a couple of hypothetical scenarios that illustrate how this payment method can be beneficial.
James, a 45-year-old father, passed away unexpectedly, leaving his young children and spouse behind. James had a life insurance policy worth $500,000. The designated beneficiary, Sarah, opted for a split payment plan, receiving $100,000 immediately to cover immediate funeral expenses, outstanding debts, and housing costs. The remaining $400,000 was divided into fixed payments of $1,000 per month over the next 33 years. This arrangement enabled Sarah to manage her finances and plan accordingly while knowing she had a consistent income stream to support her children's upbringing and daily needs.
Maria, age 75, has a long-term care insurance policy that will help cover her healthcare costs as she ages. She opted for a split payment arrangement that provides her with $2,000 monthly for her healthcare expenditures. By choosing this route, Maria ensures she maintains a steady stream of income to meet her healthcare needs while preserving some assets for her heirs. In this way, the split payment plan offers her peace of mind and financial stability during a potentially vulnerable time.
Navigating the intricacies of split insurance payments can sometimes be daunting, especially for beneficiaries who may not be well-versed in financial matters. Here are some steps that can help ensure a smooth process:
Understanding all the specifics of your policy is crucial. Review terms regarding payments, schedules, and any conditions that may affect the distribution of funds. Ensure to clarify any points of uncertainty with your insurance agent.
Engaging with financial advisors who specialize in insurance and financial management can help beneficiaries navigate their options more efficiently. These professionals can provide tailored advice regarding the implications of split payments, helping clients understand how to make the most of their insurance benefits.
Maintaining open communication with the insurance provider can ensure clarity about expectations, timelines, and payment schedules. Addressing any discrepancies directly can prevent complications that may arise later.
Prepare for unexpected financial needs that may arise. Having a plan in place regarding how to address unexpected expenses will allow beneficiaries to remain confident in their financial strategy, even in times of tight cash flow.
When opting for split insurance payments, such arrangements must comply with legal regulations that govern the insurance industry. This includes specific requirements related to consumer rights, transparency, and fair practices. Policyholders should ensure that they understand the legal framework surrounding their insurance agreements and how they affect their financial responsibilities and entitlements.
The structured approach of 분할 보험금 can provide a nuanced solution for beneficiaries to manage their finances effectively while still benefiting from the protection that their insurance policy offers. While spreading out payments can indeed mitigate some financial pressures, it's critical for insurers and policyholders to weigh the associated costs and logistical challenges carefully.
In a landscape that is continuously evolving, particularly with the advancing economic conditions and other uncertainties, understanding the strategic benefits and implications of 분할 보험금 becomes increasingly important. As policyholders assess their individual circumstances and financial goals, such clarity can aid in making informed decisions that align with their life situations and aspirations, ultimately leading to better financial outcomes.
As with any financial strategy, the success of split insurance payments hinges on informed choices that take both personal and broader economic factors into account. By doing so, stakeholders can navigate their financial futures with greater confidence and stability.




Digital insurance companies, known as 디지털 손해 보험사, are reshaping the insurance landscape by leveraging technology to offer efficient, user-friendly services. These companies differ from traditional insurers by emphasizing digital platforms for operations, creating a seamless customer experience. This article delves into the critical aspects of digital insurance firms, exploring how they function and their benefits to consumers.

This guide delves into the realm of 다이렉트 건강 보험, highlighting its unique structure within the health insurance sector. 다이렉트 건강 보험 is a system that allows consumers to purchase health insurance directly without intermediaries, often resulting in cost savings and tailored plans. This comprehensive analysis explores its benefits, considerations, and frequently asked questions to help consumers make informed choices.

Discover the intricate process of claiming surgery costs under pet insurance (반려동물보험 수술비 청구 방법) to safeguard the health of your cherished furry companions. Pet insurance has become an integral aspect of responsible pet ownership, allowing pet parents to ensure their pets receive optimal medical care without incurring prohibitive costs. This guide provides expert insights into navigating the pet insurance landscape successfully.

This guide delves into 카이저 보험, a renowned name in healthcare provisioning. Known for its integrated care approach and straightforward insurance plans, 카이저 보험 stands as a model of efficiency in health management. By merging medical care services with insurance coverage, it aims to streamline patient experience and ensure accessible, comprehensive healthcare solutions.

As healthcare costs soar globally, mini cancer insurance plans like 미니 암 보험 become crucial for protecting the financial well-being of individuals facing cancer. This coverage, often more affordable than comprehensive plans, provides targeted benefits designed to ease the burden of expenses associated with cancer treatment and recovery. It's essential for consumers to discern their specific needs and compare different offerings.

This article explores the domain of 다이렉트 건강 보험, also known as direct health insurance, to provide a comprehensive understanding of its dynamics and impact on individuals seeking coverage. The discussion delves into the benefits and challenges of opting for direct health insurance, while also touching upon various factors such as cost-effectiveness and accessibility that influence consumer choices in the insurance market.

