This article delves into the nuances of 다이렉트 건강 보험, or direct health insurance, offering a comprehensive analysis from an expert perspective. Direct health insurance provides a streamlined approach to healthcare coverage, often removing intermediaries to potentially reduce costs and enhance personalized customer service.
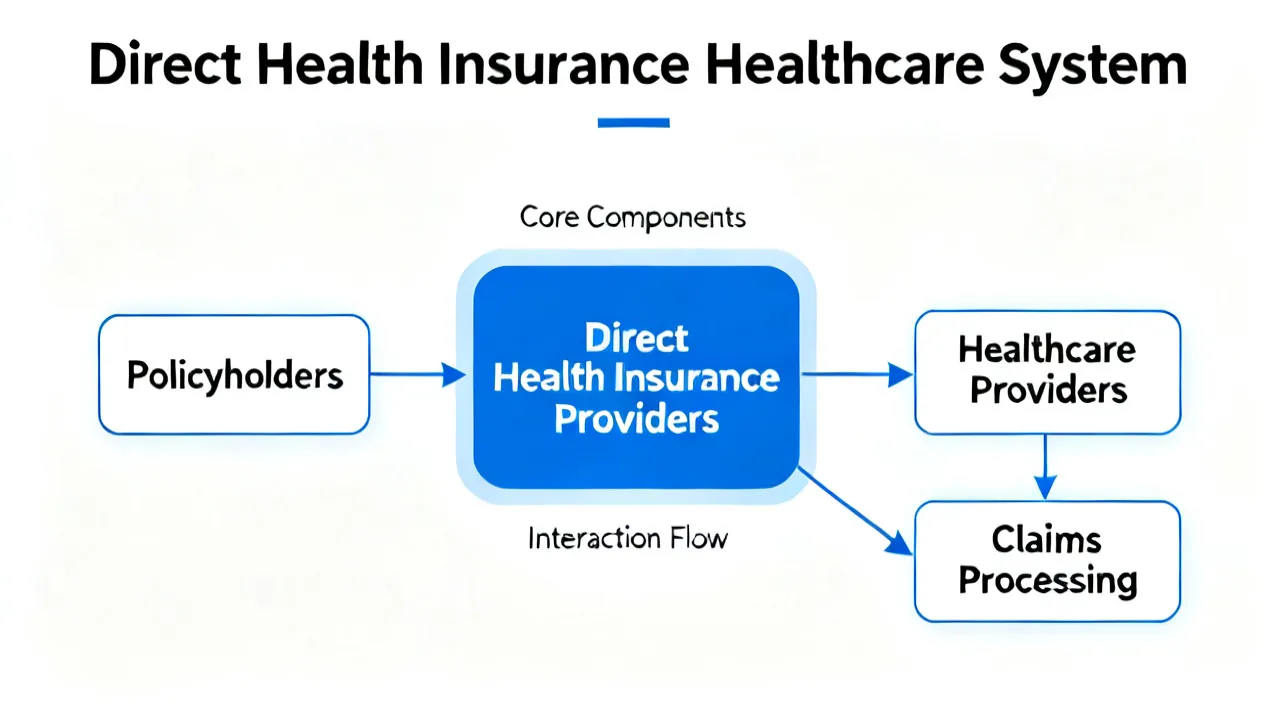
In the rapidly evolving landscape of healthcare, 다이렉트 건강 보험, or direct health insurance, emerges as an innovative model that emphasizes transparency and efficiency. Unlike traditional health insurance plans, which often involve intermediaries like brokers or agents, direct health insurance aims to provide a more direct relationship between the insurer and the insured. This approach can lead to significant cost benefits and tailored services, making it increasingly appealing in today's market. With the advent of digital platforms, most direct health insurance providers offer online resources for customers to conduct research, understand policies, and obtain quotes with unprecedented ease. By forging this direct connection, both parties can communicate more effectively, resulting in better service delivery and a smoother claims process.
Direct health insurance offers multiple advantages, primarily revolving around simplicity and cost-effectiveness. By eliminating intermediaries, these insurance plans often have reduced administrative costs, which can translate into lower premiums for the insured. For instance, when a customer interacts directly with the insurer, information is communicated faster, leading to quicker decision-making and more efficient claims processing. Furthermore, consumers have the opportunity to engage with the insurance company more readily, allowing for the customization of policies according to individual healthcare needs.
With more control over the specifics of their policies, consumers can often better match their coverage to their unique needs without unneeded extras, thus optimizing their healthcare spending. This ability to customize allows individuals to select benefits that are particularly relevant to them—such as maternity coverage, preventive care, or chronic disease management—enabling them to create a plan that genuinely reflects their lifestyle and health requirements. Additionally, because many direct health insurance plans utilize modern technology for tracking claims and policy management, users benefit from real-time insights into their coverage and health expenditures.
Typically, direct health insurance involves a one-on-one relationship between the insurance provider and the policyholder. This structure allows for more straightforward communication, faster claim processing, and often more personalized customer service. Providers focus on leveraging technology to streamline policy administration, offer instant quotes, and provide online policy management tools to enhance user experience. Many companies have begun employing telehealth services as part of their offering, which has been increasingly important in light of changing consumer behaviors and preferences.
Moreover, the operational framework ensures that providers retain greater accountability for their services, requiring them to maintain high standards in customer support. In direct health insurance models, policyholders often have access to chatbots and 24/7 customer service through apps, allowing them to resolve issues or get answers to their questions without unnecessary delays. The ease of access to claims and coverage information via mobile applications also reflects the industry's shift towards a more consumer-centered service.
Additionally, the direct health insurance model opens the door for insurers to provide wellness programs and preventive care incentives that help to foster healthier lifestyles among policyholders. These initiatives, which may include fitness memberships or personalized health coaching, further emphasize the proactive management of health and reduce reliance on more costly medical interventions down the road.
When considering switching to a direct health insurance provider, several vital factors should be taken into account:
Furthermore, it is beneficial to inquire about the insurer's reviews regarding their claims handling process. Is it straightforward, or do clients often face challenges? Policies can look attractive on paper, but if the underlying claims process is cumbersome, it may lead to dissatisfaction down the line. It's also advisable to understand the insurer’s process for adjusting premium levels over time, as sudden increases can impact long-term affordability.
Recent trends suggest a growing inclination towards direct health insurance models, particularly as technology simplifies many processes within the industry. The digital transformation enables easier access to personalization and transparency in policies. With technology increasingly integrated into health insurance products, companies are opting for data analytics to better cater to their clients’ needs, predicting future healthcare demands based on historical data.
Moreover, the COVID-19 pandemic has heightened the demand for more tailored, responsive healthcare solutions, which direct health insurance plans are well-positioned to provide. As more individuals prioritize health and wellness, innovative insurance models that include virtual care and telemedicine options are increasingly relevant. These services facilitate healthcare access for individuals who may find it challenging to visit a physician in person, thus supporting ongoing health management without interruption. The flexibility and efficiency of direct health insurance models are proving invaluable in a world that demands agility and responsiveness in care delivery.
Additionally, the rising costs of healthcare have created a pressing need for models that limit expenses while improving access to quality care. As consumer protection regulations evolve, insurers face increased pressure to provide more transparent pricing and coverage structures. This evolution influences traditional insurers to adapt their offerings, potentially creating more competition in the direct insurance market and benefiting consumers overall.
| Aspect | Traditional Health Insurance | Direct Health Insurance |
|---|---|---|
| Mediation Level | Involves multiple intermediaries | Direct relationship with insurer |
| Administrative Costs | Higher due to intermediaries | Lower, allowing cost savings |
| Customer Service | Standardized, often less responsive | More personalized and immediate |
| Technology Use | Slow adoption, manual processes | Fast adoption, digital-driven |
| Policy Customization | Limited options for personalization | High levels of customization available |
The advantages of direct health insurance become even more evident alongside these comparisons. As consumers become more educated about their choices and take proactive steps to manage their healthcare needs, the demand for direct models will continue to grow.
Direct health insurance represents a significant shift towards more consumer-centric healthcare solutions. By focusing on cost savings, efficiency, and personalized care, these models address the increasing demand for transparency in healthcare. As the industry continues to embrace technological advancements, particularly in data utilization and digital engagement, the landscape of health insurance is poised to evolve dramatically. This evolution holds the promise of reshaping how individuals interact with their healthcare providers and manage their health insurance policies, as they seek options that align with their values and needs. In this increasingly complex world of health insurance, understanding the advantages of direct models can empower consumers to make informed decisions that promote better health outcomes and enhance their overall healthcare experience.




Digital insurance companies, known as 디지털 손해 보험사, are reshaping the insurance landscape by leveraging technology to offer efficient, user-friendly services. These companies differ from traditional insurers by emphasizing digital platforms for operations, creating a seamless customer experience. This article delves into the critical aspects of digital insurance firms, exploring how they function and their benefits to consumers.

This guide delves into the realm of 다이렉트 건강 보험, highlighting its unique structure within the health insurance sector. 다이렉트 건강 보험 is a system that allows consumers to purchase health insurance directly without intermediaries, often resulting in cost savings and tailored plans. This comprehensive analysis explores its benefits, considerations, and frequently asked questions to help consumers make informed choices.

Discover the intricate process of claiming surgery costs under pet insurance (반려동물보험 수술비 청구 방법) to safeguard the health of your cherished furry companions. Pet insurance has become an integral aspect of responsible pet ownership, allowing pet parents to ensure their pets receive optimal medical care without incurring prohibitive costs. This guide provides expert insights into navigating the pet insurance landscape successfully.

This guide delves into 카이저 보험, a renowned name in healthcare provisioning. Known for its integrated care approach and straightforward insurance plans, 카이저 보험 stands as a model of efficiency in health management. By merging medical care services with insurance coverage, it aims to streamline patient experience and ensure accessible, comprehensive healthcare solutions.

As healthcare costs soar globally, mini cancer insurance plans like 미니 암 보험 become crucial for protecting the financial well-being of individuals facing cancer. This coverage, often more affordable than comprehensive plans, provides targeted benefits designed to ease the burden of expenses associated with cancer treatment and recovery. It's essential for consumers to discern their specific needs and compare different offerings.

This article explores the domain of 다이렉트 건강 보험, also known as direct health insurance, to provide a comprehensive understanding of its dynamics and impact on individuals seeking coverage. The discussion delves into the benefits and challenges of opting for direct health insurance, while also touching upon various factors such as cost-effectiveness and accessibility that influence consumer choices in the insurance market.

