This guide delves into the domain of 의료실 비보험, exploring its impact on healthcare costs and accessibility. 의료실 비보험, or medical office non-insured services, refers to healthcare procedures and treatments not covered by standard health insurance plans. As healthcare systems globally struggle with rising costs, understanding the nuances of 비보험 services becomes crucial for patients seeking affordable care.
The healthcare landscape is rapidly evolving, with increased patient awareness and demand for diverse medical services. Key among these is the concept of 의료실 비보험, which is steadily gaining recognition. Essentially, 의료실 비보험 refers to non-covered medical office services. These services are typically not reimbursed by conventional insurance plans, placing a financial responsibility directly on the patient. As more patients seek out services that align with their individual health needs, understanding 의료실 비보험 has become crucial in navigating the often complex world of healthcare coverage.
In traditional health insurance models, a range of treatments and procedures are covered, ensuring that patients incur minimal out-of-pocket expenses. However, when it comes to 비보험, these services fall outside the insured framework. This can include elective procedures, alternative therapies, or specialized consultations that are deemed non-essential by insurers. Many patients find themselves unprepared for the financial implications tied to these non-covered services, leading to unexpected healthcare spending that can disrupt family budgets and financial stability.
The distinction between insured and non-insured services often hinges on medical necessity, cost-efficiency, and policy guidelines. Insurance companies assess a procedure’s necessity based on clinical evidence and cost factors. Procedures lacking substantial evidence of efficacy or those intended for cosmetic purposes frequently end up in the 비보험 category. Furthermore, the criteria can also include the perceived benefit versus the cost incurred, where insurers opt not to cover services they believe do not meet their value benchmarks. This situation often leaves patients questioning the rationale behind their insurance plans and the healthcare services they require.
As patients increasingly encounter services that fall under 비보험, there is a pressing need for effective cost management. Understanding the dynamics of healthcare expenses associated with 비보험 services can empower patients. Here are some strategies they can employ:
Patient advocacy plays a critical role in managing 비보험 services effectively. Patients should not hesitate to advocate for their needs within the healthcare system. This includes:
Advocating for oneself can lead to more informed decisions about medical care and financial planning.
Globally, the integration and management of 비보험 vary considerably. In countries with comprehensive public health systems, such as the UK or Canada, government-funded services are extensive, limiting the 비보험 category to largely elective services. These disparities in how healthcare is organized can greatly influence patient experiences and expectations. On the other hand, in markets like the USA, where private insurance dominates, the scope of 비보험 is broader, leading to more pronounced discrepancies in patient access and affordability.
| Country | Non-Insured Services Regulation |
|---|---|
| USA | Predominantly reliant on private insurance, leading to a broad spectrum of uninsured services such as cosmetic surgeries, certain dental services, and non-traditional therapies. |
| Canada | Public health system minimizes 비보험, focusing services mostly on electives; patients generally do not pay out-of-pocket for consultations, necessary surgeries, and hospital stays. |
| UK | NHS covers an extensive range; 비보험 is limited to specialized non-essential services such as certain dermatological procedures and cosmetic changes. |
This comparative analysis illustrates how different healthcare systems approach the challenge of non-insured services and how these policies can directly affect patient experiences and financial outcomes.
Regulations governing 비보험 practices differ by region, influenced by national healthcare policies and insurance industry norms. Policymakers are tasked with balancing the scales between cost control and patient access, prompting debates on coverage expansions and the ethical implications of denying necessary care. This can lead to significant discussions about the role of insurance companies in determining what constitutes 'necessary' medical care.
Q: What types of services typically fall under 의료실 비보험?
A: This often includes elective surgeries, cosmetic procedures, and some alternative therapies. Services like plastic surgery, aesthetic treatments, and wellness therapies are common examples.
Q: How can patients predict which services will be non-insured?
A: Discussions with healthcare providers about treatment plans and insurance coverage details can clarify potential costs. Additionally, reviewing the patient's insurance plan documents can provide insights into which services are covered and which may be considered 비보험.
Q: Are payment plans commonly available for 비보험 services?
A: Yes, many providers offer flexible payment options to assist with managing costs associated with 비보험 services. This option can be crucial for patients who want to access medical treatments without facing significant immediate financial pressure.
Q: How do 비보험 services impact overall healthcare accessibility?
A: They can hinder access for low-income patients unable to afford additional out-of-pocket expenses, highlighting the need for comprehensive coverage discussions. The existence of 비보험 categories can create barriers to necessary care, often shifting the burden disproportionately onto vulnerable populations.
To better understand the complexities surrounding 비보험 services, we look into several case studies that highlight different scenarios involving healthcare providers, patients, and insurance companies. These examples illustrate the real-world implications of navigating 비보험 and can provide valuable insights.
In the United States, a patient named Sarah sought to undergo a breast augmentation procedure. This procedure was classified as cosmetic and, thus, was categorized under 비보험. Facing a total cost of $8,000, she found herself in a strenuous decision-making process. After reviewing her options, Sarah consulted with multiple plastic surgeons and was able to negotiate a payment plan with one of them, allowing her to manage her expenses over several months. Sarah's experience underscores the necessity for patients to proactively engage with healthcare providers regarding potential payment options for 비보험 services.
John, a resident of Canada, opted for an elective knee surgery that his physician recommended. Due to specific circumstances, the procedure fell outside the public health system's coverage. However, John had been diligent in setting up a Health Savings Account (HSA) for such situations. Using his HSA, John was able to cover the $3,500 cost efficiently. His case emphasizes how proactive financial planning can mitigate the impact of 비보험 services and help patients afford necessary treatments without significant financial strain.
Emily, a patient in the UK, decided to pursue acupuncture for chronic pain relief. Although this therapy provided significant improvements in her quality of life, it was not covered under the National Health Service (NHS) guidelines. Consequently, she had to pay out-of-pocket for each session. To manage these expenses, Emily sought out community programs offering discounted sessions and formed a shared group with other patients to split costs on monthly treatments. This case illustrates how users of 비보험 services can still seek affordable options and support systems within their communities.
As the landscape of healthcare continues to evolve, understanding 비보험 becomes increasingly important. Patients must navigate the nuances of non-covered services to make informed decisions about their health care and finances. Recognizing the variety of strategies available for managing these costs, advocating for personal health needs, and staying informed about the global dynamics of healthcare can empower patients in their journey.
Moreover, as healthcare regulations and policies continue to shape the services available to patients, ongoing discussions about the need for comprehensive coverage are essential. As patients advocate for their needs in the healthcare system, they can help drive changes that promote greater accessibility and affordability in healthcare services, allowing for a healthier society overall.



Receiving a lung cancer diagnosis is not only a medical shock but an emotional one as well, particularly when it comes to telling your family. These heart-to-heart talks are laden with feelings and pose difficulties for everyone involved. To navigate these discussions about a lung cancer diagnosis with your loved ones, consider the following strategies.
Selecting an adept dental implant specialist is crucial, as it significantly impacts the success of your procedure and satisfaction with the experience. Carefully evaluating factors and the specialist's qualifications ensures their proficiency and capacity to meet your individual needs. This resource will shed light on key points and tactics for making an informed choice that promises excellent outcomes and a positive procedural journey.
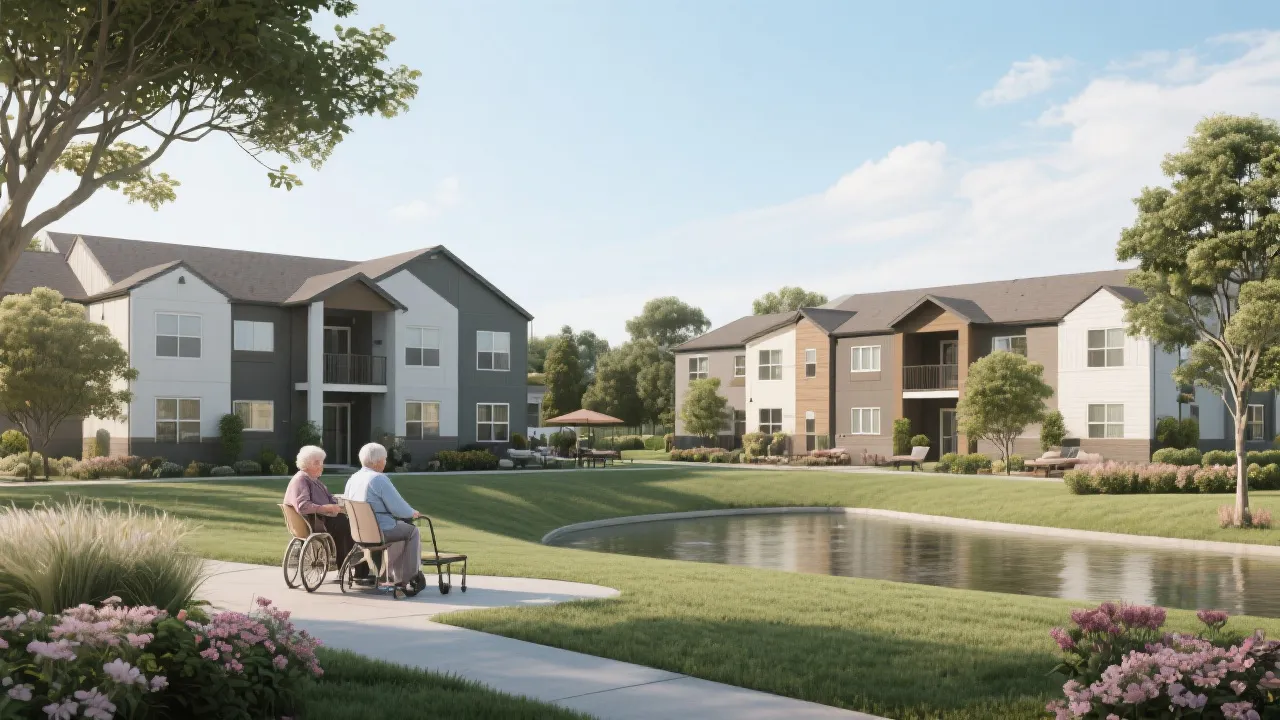
Heartis Eagle Mountain is at the forefront of senior living communities, offering comprehensive care and lifestyle options for older adults nearby. Located in a picturesque environment, it combines comfort with high-quality services to support various needs. As an example of pristine senior living, Heartis Eagle Mountain provides a blend of independent lifestyle, assisted living, and memory care, tailored to the individual requirements of its residents.
Globally, lung cancer ranks as a top cause of cancer mortality, often going unnoticed due to its initially understated symptoms. Prompt recognition leads to better survival rates and therapeutic results, highlighting the importance of awareness in combating this dangerous illness. We explore five key early warning signs to help identify lung cancer sooner.
Participating in athletics and fitness regimens is undoubtedly beneficial for one's overall fitness. Yet, such endeavors carry inherent dangers, including potential harm to one's oral region. Taking strategic measures can, however, safeguard your dental health, allowing you to revel in the sports you love.
Choosing an expert for your dental implant surgery is crucial, as it greatly impacts the final result. The right expert, who is knowledgeable, seasoned, and caring, can enhance the likelihood of success, making the procedure efficient, effective, and comfortable. This detailed guide aims to help you find a dental implant specialist aligned with your needs, ensuring a gratifying outcome.

